If you are planning this fall the way you planned last fall, you are solving the wrong problem.
You know the shape of the season already. Harvest runs into back-to-school, Halloween, and the holiday build, and whatever you did not sort out in July, you pay for in November. What changes year to year is where the squeeze comes from.
This year it did not come from imports. The wave that normally lands on top of harvest already came and went. May was the busiest month of 2026 and volumes have eased every month since, so most of your Q4 inventory is already sitting in a DC. The containers are not the problem.
The trucks are. Tender rejections have more than doubled since January, diesel is up almost two dollars a gallon year over year, and 50,000 carriers have left the market in twelve months.
Soft imports, tight trucks. Plan for capacity, not volume.
Why Fall Shipping Is Different From Other Seasons
The demand drivers stacked up in the wrong order this year. Imports peaked early and then faded. May was the busiest month of 2026 at 2.24 million TEUs, and by July, Los Angeles and Long Beach were down 5.8% and 1.7% year over year. Most of the freight that would normally be landing right now is already sitting in a domestic DC. Your Q4 problem is not getting containers off the water. It is finding trucks for freight that is already in the building.
Calm weather can create a false sense of security. NOAA forecasts 7 to 13 named storms and a 75% chance of below-normal activity, while Colorado State puts the odds of a Category 3 or stronger U.S. landfall at 16%, compared with the 43% historical average. The greater concern may be a Gulf Coast refinery disruption in a tight diesel market, while early October snow could complicate linehaul and yard operations farther north.
What Changed for Fall 2026: A Tight Truck Market
If you planned last fall’s peak, plan this one differently. The truckload market turned between January and August, and the shift is big enough to change how far ahead you book.
- Tender rejections sit at 13.6%, up from a cycle low near 6% in January. Analysts now read 12 to 13% as the marker of a tight market. The old threshold was 8%.
- Spot rates are running 34 to 38% above last year across van, reefer, and flatbed. DAT’s July all-in averages: $3.01 van, $3.42 reefer, $3.64 flatbed.
- Spot and contract van rates hit parity in July. That is a market-turn signal, not equilibrium. Contract van rose 12 cents month over month and reefer 7 cents, the largest June-to-July gains DAT has recorded.
- Capacity left the market. More than 50,000 carriers have exited in twelve months, and truck transportation employment has fallen year over year for 38 straight months.
- Diesel is the wild card at $5.65 a gallon, up $1.94 year over year. This is a refining problem, not a crude problem, and it is why LTL rate per pound is up 5.9% while fuel surcharges run more than 60% above June 2025.
The practical consequence is that the six-to-eight-week booking window below is a floor this year, not a target. Shippers who move on Q4 bids early are the ones who will not be buying November capacity at spot.
Three Rule Changes Removing Trucks From the Market
Capacity is not only leaving for economic reasons. Three enforcement actions are pulling drivers and equipment out on their own schedule, and each one matters for peak planning.
- Non-domiciled CDLs. The FMCSA rule effective March 16, 2026 limits non-domiciled CDLs to H-2A, H-2B, and E-2 visa holders. FMCSA estimates 97% of roughly 200,000 current holders cannot requalify, about 5% of all U.S. CDLs. Existing licenses run until they expire, so this drains capacity gradually into 2027 rather than all at once.
- English language proficiency. A violation carries an immediate out-of-service designation. Enforcement has removed drivers at roughly 20,000 a year since June 2025, concentrated in California, New Jersey, New York, and Florida.
- ELD certification. More than 56 devices have been revoked since January 2026 under stricter vetting. A revocation strands a fleet, so confirm your carriers’ ELD providers are still on the registered list before peak.
LTL shippers have a fourth item. NMFTA’s Docket 2026-1, effective February 6, 2026, continues the density-based restructuring that started in July 2025. Audit your NMFC codes and confirm your BOLs and TMS carry accurate weights and dimensions, or you will spend your busiest weeks arguing reclassifications and rebills. Our guide to NMFC codes and freight class walks through the audit.
Industries and Commodities Driving Fall Freight
Harvest sets the fall calendar, and this year the crops pull in different directions.
Agriculture and produce
- Pacific Northwest (WA/OR): Apples and pears ship August through November, but USDA has the 2026 U.S. apple crop down 6% year over year, and Washington growers expect a smaller season after an April frost.
- Cranberries (WI/MA): Harvest and shipments peak September through November.
- Pumpkins (IL/Midwest): Illinois is still the country’s largest producer. Our produce season freight guide covers how these windows move capacity.
- Sweet potatoes (NC): North Carolina has led U.S. production since the 1970s, with harvest ramping into Thanksgiving.
- Soybeans (Midwest): The largest U.S. crop on record, 4.52 billion bushels on 5.3 million more harvested acres, while corn falls 5.9%. This is the biggest single change to fall lane mix.
Food and beverage
- Halloween candy: Halloween spending set a record $13.1B in 2025, and NRF publishes its 2026 forecast in late September. Either way, reefer and dry van demand spikes through September and early October as manufacturers and DCs push replenishment.
- Thanksgiving staples: Reefer volumes and rates firm ahead of the holiday for proteins, produce, and desserts. See our guide to reefer LTL if you are moving temperature-controlled freight in smaller lots.
Retail and e-commerce
- Back-to-school through Cyber Monday: Imports arrived early because Section 122’s flat 10% tariff expired July 23 and Section 301 forced-labor tariffs replaced it the next morning, stacking China to 37.5%. Retailers pulled Q4 inventory forward ahead of the switch. NRF now projects only modest year-over-year port growth from September through December, so align DC labor and transportation lead times to freight that has largely already landed.
Regional Shipping Patterns Across the US
- Midwest (IL/IA/IN/OH/MI): Record soybean crop moving toward Gulf and Pacific Northwest export elevators. Expect van and reefer capacity to tighten along I-55 and I-74.
- Pacific Northwest (WA/OR/ID): Apples and pears surge August through November. Watch Yakima and Wenatchee reefer demand.
- Northeast (NY/NJ/PA): Retail replenishment tracks Port of NY/NJ volumes, which followed the same early-then-flat 2026 pattern as the West Coast.
- Southeast and Gulf (FL/GA/AL/MS/LA/TX): Hurricane risk runs through November even in a below-normal season. Keep contingency routings through inland ramps and secondary ports, and watch refinery exposure specifically, because a storm there moves diesel before it moves lanes.
- West Coast (CA): Central Valley produce and heavy LA/LB transload continue, but early import front-loading changes October capacity dynamics.
Carrier Behavior and Capacity Shifts
Carriers follow the money. In the fall that means repositioning toward harvest and retail lanes and prioritizing the higher-paying freight, with reefer carriers shifting hardest toward the holiday food surge. Thanksgiving week is the reliable pinch point. Drivers take time off, spot capacity tightens, and tender rejections and rates usually jump the week before. Plan around that week, not into it.
Shippers with the flexibility are leaning harder on milk runs, pool distribution, and LTL consolidation to protect service and cost. If you are shifting volume that way, check current LTL transit times before you commit to a receiving window.
Top Pitfalls for Shippers
- Booking too late, especially reefers, and ignoring LTR and OTRI signals that were flashing weeks earlier.
- Missing holiday cutoffs as retail receiving calendars compress.
- Relying on a single carrier instead of layered capacity.
- Skipping weather contingencies such as alternate ports or ramps.
- Under-communicating with suppliers, which shows up as ASN inaccuracy and OTIF penalties.
Key Metrics to Monitor in Fall
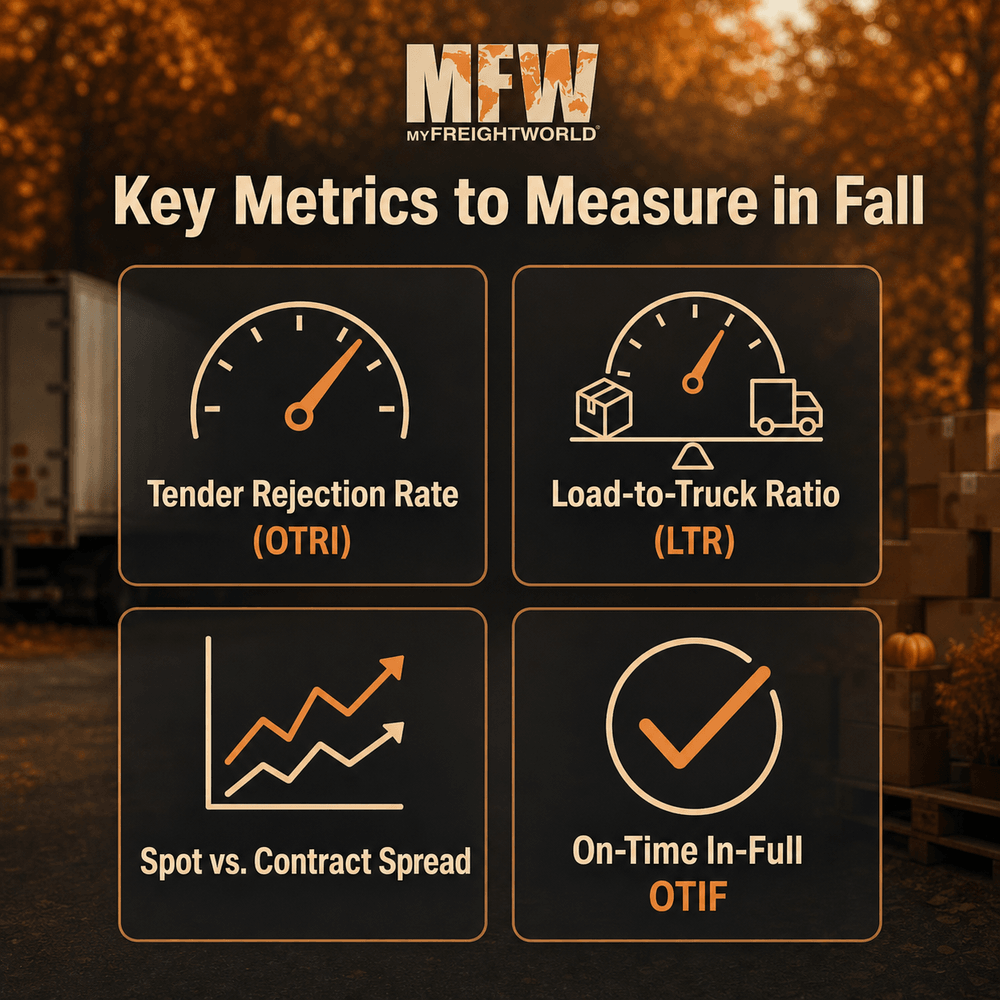
- Tender rejection rate (OTRI): Leading indicator of tightening.
- Load-to-truck ratio (LTR): Real-time spot demand versus capacity, and it usually moves before rates do. Watch reefer LTR in the Pacific Northwest and Midwest, van LTR near port-proximate markets.
- Spot vs. contract spread: A narrowing spread means your bid leverage is shrinking.
- OTIF: The compliance number that matters most going into the holidays.
- Inventory turns and DC dwell: Rising dwell or slowing turns usually precede expensive expedites.
These sit alongside the top transportation metrics for 2026.
Shipper Action Plan
- Forecast off this year, not last year. Build load plans from harvest calendars and port projections. The early import peak means last year’s shape will mislead you.
- Secure capacity earlier than feels necessary. Lock lanes six to eight weeks out at minimum and set pre-approved spot guides for the harvest and retail lanes you know run hot. If you are weighing how much volume to commit, compare dedicated versus spot truckload.
- Grade last year’s carriers, then concentrate volume. Review delivery speed, surcharge behavior, and on-time reliability. Give more freight to the carriers that held up, and spread the rest wide enough that one bottleneck cannot stall you.
- Optimize modes and routes. Pool distribution, merge-in-transit, and intermodal where transit allows. Reserve reefer capacity specifically for Halloween and Thanksgiving.
- Budget for the cost side honestly. Plan for peak surcharges and fuel swings and set money aside for the busiest weeks instead of absorbing surprises in December.
- Handle cross-border first. Those lanes spike hardest. Secure capacity early and use carriers experienced with the customs paperwork.
- Communicate and monitor. Share ASN accuracy goals with suppliers, adjust receiving calendars around November 1 and holiday closures, and review OTRI, LTR, and rate spreads weekly so you can trigger a mini-bid or mode shift while you still have options.
The Bottom Line
Fall 2026 is soft imports against the tightest truck market since 2022, layered on the same harvest-to-holiday cadence you already know. That combination punishes shippers who plan on volume alone and rewards the ones who plan on capacity. Book earlier than last year, watch the leading indicators weekly, and keep alternate routings ready for a diesel market that one Gulf storm could tighten further.
Ready to lock in your fall lanes? Talk to MyFreightWorld about a rapid fall readiness review and lane-by-lane capacity plan.